Home / Specialist mortgages / Let to Buy Mortgage
Let to buy
Moving without selling? A let to buy mortgage lets you rent out your current home and buy your next one. Get in touch for a free, no-obligation chat with an adviser.
Your first consultation is free. Leave your details and an adviser will call you back.
Let to buy — a guide
If you have a standard residential mortgage and want to let your home to tenants, you’ll need to move it onto a let to buy mortgage. Many applicants — often called “accidental landlords” — use it to keep their existing property when they move.
You’ll normally have two mortgages at once, not necessarily with the same lender: one on the home you’re letting, and one on your new home. It isn’t legal to let your home without the right mortgage in place, unless you own it outright.
It can help in lots of situations, provided you meet the criteria. Common examples:
It varies by lender, but typically:
Depending on your mortgage terms, your lender may grant “consent to let” — useful if you’re moving in with a relative who needs care, or working abroad for a short time.
Speak to an expert
Our advisers are experienced in a wide range of clients, needs and property types — so you can be confident of quality service and sound advice.
Useful links
Why Energise Mortgages?
01
A stamp duty surcharge applies when you buy a property in addition to one you already own. Rates change, so we’ll confirm the current figure — and factor it into your rental and affordability calculations.
02
Let to buy is seen as higher risk, so rates are usually less competitive than standard residential mortgages, particularly on the high street.
Managing two mortgage payments and the tax implications of becoming a landlord are real responsibilities — expert advice and careful research into rental income help balance them.
03
Buy to let mortgage. In some cases you can remortgage your current home onto a buy to let mortgage and take a separate residential mortgage on your new home.
Second charge mortgage. If there’s enough equity in your current home, a second charge can help fund your new purchase.
04
Let to buy applications can be complex, but they’re a viable option for many homeowners who want to move without selling. We’ll explain your options clearly and find the lender offering the best let to buy deal for your circumstances.
Related guides
Your home may be repossessed if you do not keep up repayments on your mortgage.
The Financial Conduct Authority does not regulate some buy to let mortgages.
Meet the adviser
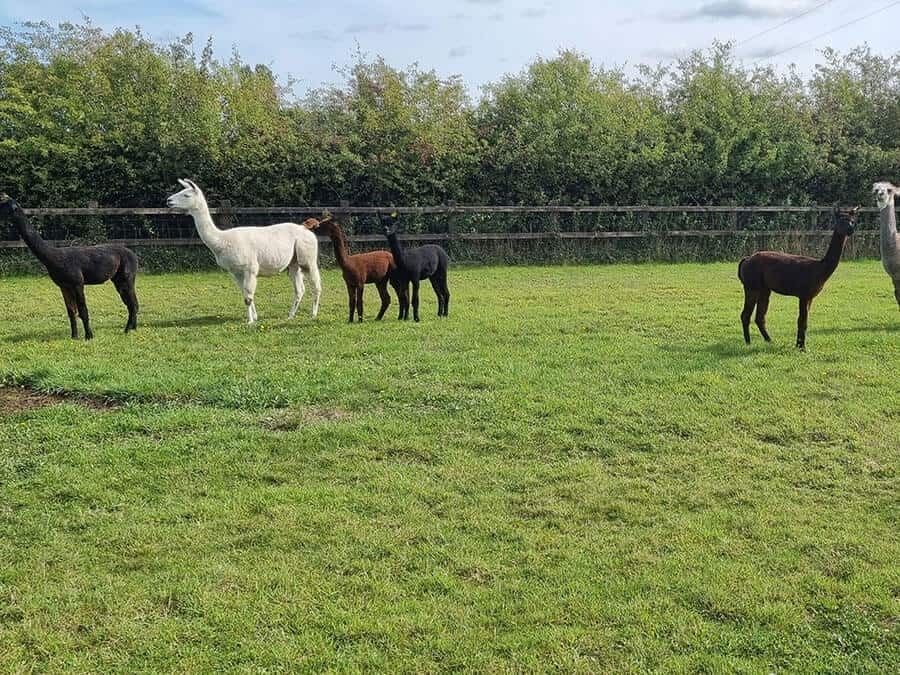
There’s more to me than just mortgages. I also have a love for the countryside and a unique venture — my alpaca farm. Nestled in the countryside near York, my alpacas are not just my furry friends, but also a testament to my dedication to diverse interests.
Alpacas, much like mortgages, require careful attention, understanding and a keen eye for detail. Just as I meticulously evaluate mortgage options, I apply the same diligence to caring for my herd — a blend of financial acumen and agricultural expertise that sets me apart.
Google reviews
“I had a fantastic experience with Steven as my mortgage broker. He was professional, knowledgeable and incredibly helpful throughout the whole process.”
Arnaldo KB
Google review · August 2026
“Steven gets it. He’s been round the block and knows all the things you hire a mortgage adviser for. It’s a no-brainer — save yourself time, money and effort.”
Matt Chappell
Google review · August 2026
“Working with Steven was easily the best decision we made during our home-buying journey. As first-time buyers, he made the process feel simple.”
Kirsty
Google review · August 2026